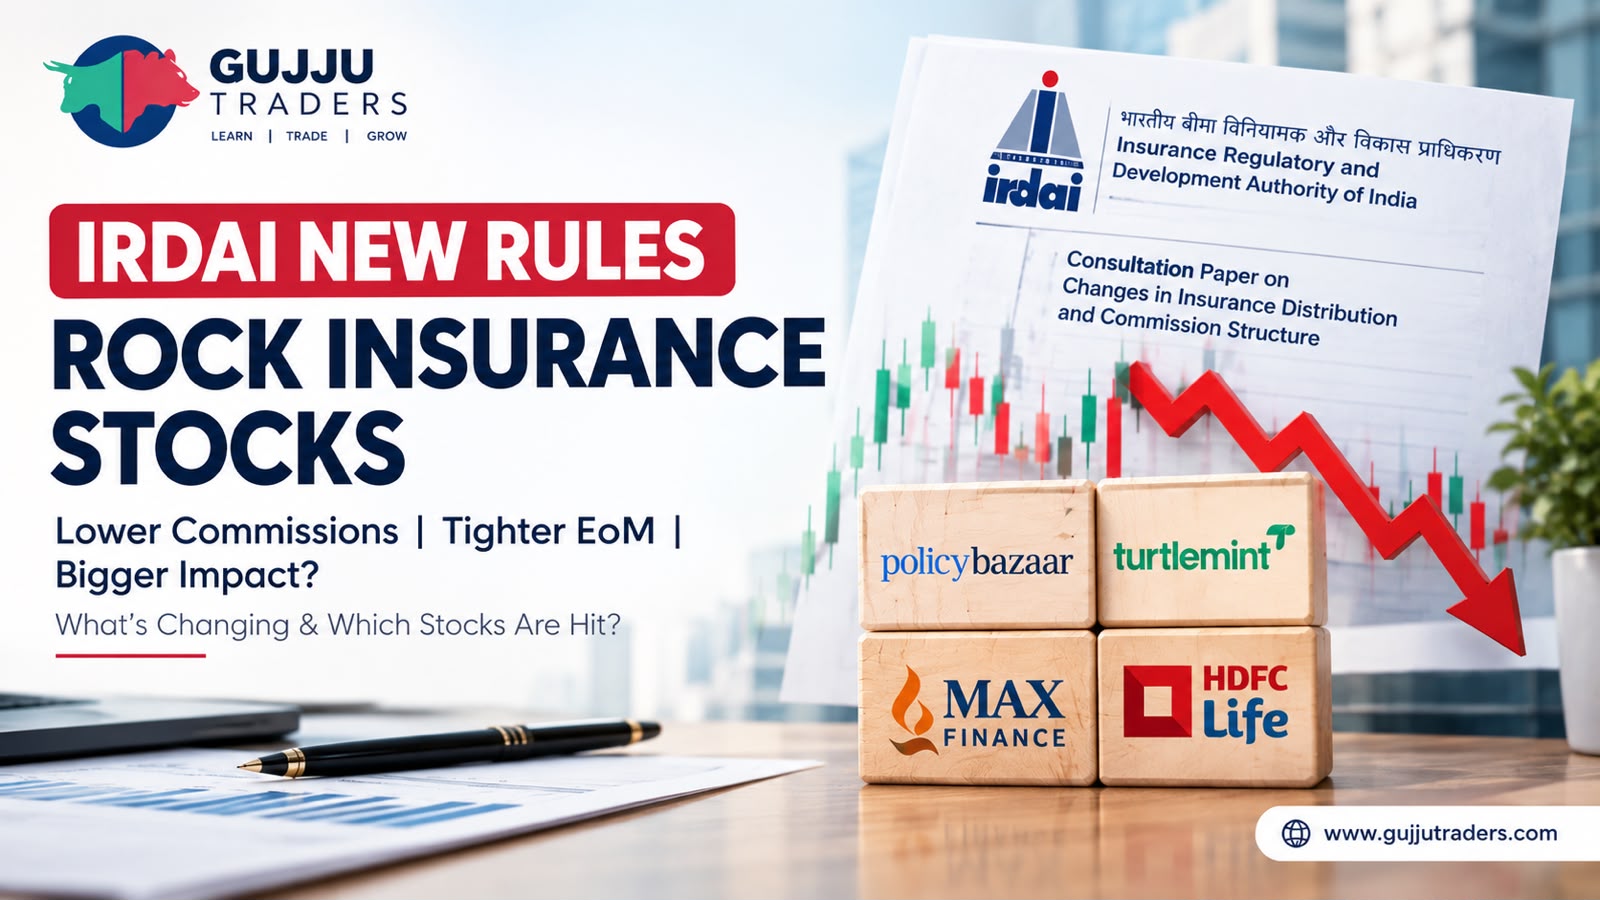
The Indian insurance sector came under significant selling pressure on September 24, 2026, after the Insurance Regulatory and Development Authority of India (IRDAI) released a consultation paper titled “Recalibrating Economics of Insurance Distribution.”
The proposal could fundamentally change how insurance companies, banks, brokers, corporate agents and digital insurance platforms earn money from selling insurance.
Stocks including PB Fintech, HDFC Life, ICICI Prudential Life, SBI Life, Max Financial, ICICI Lombard, Star Health and LIC came under pressure during Thursday’s trading session. Distribution-focused businesses experienced particularly sharp selling. (Moneycontrol)
The important point, however, is that these are consultation proposals and not final regulations yet. IRDAI has invited stakeholder comments until October 25, 2026. (The Economic Times)
What Has IRDAI Proposed?
The consultation paper covers much more than simply reducing insurance commissions.
The proposed framework addresses:
- Insurance distributor commissions
- Expense of Management (EoM)
- Bancassurance
- Loan-linked insurance
- Health-insurance renewals
- Motor insurance commissions
- Life-insurance commissions
- Mis-selling
- Digital “dark patterns”
- Insurance distribution architecture
- Bima Sugam
- Public Insurance Registry
IRDAI says the broader objective is to create a more customer-centric, competitive, efficient and transparent insurance-distribution ecosystem. (The Economic Times)
The Biggest Change: Insurance Commission Caps
One of the most important proposals is to move towards product- and channel-specific commission limits.
Instead of allowing distributors to receive broadly flexible payouts, IRDAI proposes different limits depending on:
- Insurance segment
- Product type
- Distribution channel
- Policy duration
- Product complexity
- Selling and servicing effort
This means the economics of selling a health policy could be very different from selling a long-term life policy. (Business Standard)
Proposed Commission Structure
| Insurance Product | Distribution Entity | Agent / Associate |
|---|---|---|
| Individual Health – First Year | 15% | 20% |
| Individual Health – Renewal/Porting | 5% | 10% |
| Motor TP – New Vehicle | 0% | 2.5% |
| Motor OD/PA/LL – New Vehicle | 5% | 10% |
| Life Non-linked/Linked, ≥10-year term – First Year | 20% | 25% |
| Life Non-linked/Linked, ≥10-year term – Renewal | 3% | 5% |
| Pure Term – First Year | 25% | 30% |
| Pure Term – Renewal | 7.5% | 10% |
| Large Property/Engineering risks | 5% | 5.5% |
These are proposed ceilings, not current final applicable rates. The final framework may change following consultation. (Business Standard)
Why Are Insurance Stocks Reacting So Sharply?
The market is essentially asking one question:
If distributors receive less money for selling insurance, how will the entire insurance ecosystem adjust?
There are several potential effects.
1. Distributor revenue could decline
Insurance brokers and digital platforms often earn a significant portion of their economics from commissions or distribution income.
Therefore, a reduction in commission rates can directly affect their revenue per policy.
2. Customer acquisition economics could change
Suppose a distributor currently receives ₹20 on a ₹100 premium.
If the permitted payout becomes ₹15:
Commission = ₹15 instead of ₹20
That’s a:
25% reduction in commission per policy.
For a business operating on high volumes, the impact can become significant.
3. Insurers may need to redesign distribution strategies
Insurers could respond through:
- Lower acquisition costs
- Greater use of digital channels
- More direct sales
- Higher agent productivity
- Changes in product mix
- Greater focus on persistency
The actual impact will differ by insurer.
Expense of Management — Another Major Change
The second major issue is the proposed reduction in Expense of Management (EoM).
For life insurers, IRDAI proposes moving toward:
15% of GDPI within two years
and eventually:
12.5% within five years.
For general insurers, the proposed trajectory moves from the existing 30% of GWP framework toward 20% of domestic GDPI within five years. (The Economic Times)
Proposed EoM Framework
| Category | Current Framework | Proposed Long-Term Level |
|---|---|---|
| Life Insurance | Existing EoM framework | 12.5% of GDPI |
| General Insurance | 30% of GWP | 20% of domestic GDPI |
| Life transition | — | 15% within 2 years |
| General insurance transition | — | Phased reduction over 5 years |
The objective stated by IRDAI is to reduce the overall cost of insurance and potentially improve policyholder value. (The Economic Times)
Practical Case Study 1: Health Insurance
Let’s understand the proposal using a simple example.
Suppose a customer purchases a health insurance policy with an annual premium of:
₹20,000
First-year distribution entity
Proposed maximum:
15%
Therefore:
₹20,000 × 15% = ₹3,000
Renewal
Proposed maximum:
5%
₹20,000 × 5% = ₹1,000
So the distributor’s maximum commission under the proposed framework would be:
| Year | Premium | Proposed Commission | Amount |
|---|---|---|---|
| Year 1 | ₹20,000 | 15% | ₹3,000 |
| Renewal | ₹20,000 | 5% | ₹1,000 |
| Renewal | ₹20,000 | 5% | ₹1,000 |
This illustrates why renewal-heavy insurance businesses could experience a significant change in economics.
Practical Case Study 2: Motor Third-Party Insurance
This proposal is particularly interesting.
IRDAI proposes zero commission for distribution entities on motor third-party insurance.
Suppose:
Motor TP premium = ₹5,000
Under the proposed structure:
Distribution entity commission = 0%
Therefore:
₹5,000 × 0% = ₹0
For agents/associates, the proposed figure is 2.5%:
₹5,000 × 2.5% = ₹125
This could materially alter the economics of channels that depend heavily on motor insurance distribution. (Business Standard)
Practical Case Study 3: Long-Term Life InsuranceConsider a hypothetical policy with an annual premium of:
₹1,00,000
and a premium-paying term of 10 years or more.
For a distribution entity, the proposed first-year commission ceiling is:
20%
Therefore:
₹1,00,000 × 20% = ₹20,000
Proposed renewal commission:
3%
₹1,00,000 × 3% = ₹3,000
Example
| Year | Premium | Proposed Commission | Commission |
|---|---|---|---|
| 1 | ₹1,00,000 | 20% | ₹20,000 |
| 2 | ₹1,00,000 | 3% | ₹3,000 |
| 3 | ₹1,00,000 | 3% | ₹3,000 |
| 4 | ₹1,00,000 | 3% | ₹3,000 |
Again, these are illustrative calculations using the proposed caps, not forecasts of what any particular insurer or distributor will actually pay.
The Bigger Story: Distributor Payouts Have Been Rising
IRDAI’s consultation paper highlights a significant divergence between insurance business growth and distributor remuneration.
For a sampled group of corporate agents between FY23 and FY25:
New Business Premium increased:
₹63,000 crore → ₹80,000 crore
That’s approximately:
+27%
But total distributor remuneration increased:
₹9,580 crore → ₹21,600 crore
That’s approximately:
+125%
IRDAI says distributor remuneration was around 27% of first-year life-insurance premiums in the cited sample, with additional rewards and incentives potentially adding substantially to base commissions. (Moneycontrol)
This divergence is one of the central reasons behind the proposed regulatory reset.
What About Bancassurance?
This is another area investors are watching closely.
Banks have become an important distribution channel for private insurers.
IRDAI’s consultation paper highlights wide differences in payouts associated with bank arrangements and particularly flags loan-linked insurance.
The paper notes that group credit-life payouts reached as high as 45% in FY25, compared with around 5% in FY23 in the cited data. (Moneycontrol)
The proposed framework also places lower commission limits on insurance sold alongside loans.
It additionally seeks to prevent practices involving compulsory insurance bundling with credit. (Moneycontrol)
Practical Case Study 4: Insurance Sold With a Loan
Imagine a customer takes a:
₹10 lakh loan
The lender also sells a credit-life insurance product.
Suppose, purely for illustration, that insurance premium is:
₹50,000
If the distribution payout were 20%:
₹50,000 × 20% = ₹10,000
Under a hypothetical 5% ceiling:
₹50,000 × 5% = ₹2,500
Potential difference:
₹7,500 per policy
This demonstrates why loan-linked insurance distribution economics are attracting investor attention.
The actual impact on any bank/NBFC will depend on its product mix, contractual arrangements and the final rules.
Which Stocks Are Being Impacted?
The market reaction has not been uniform.
During Thursday’s trading session, reports showed particularly sharp pressure on PB Fintech and Turtlemint, while several listed insurers also declined. At one point, reported moves included PB Fintech near a 20% lower circuit, Max Financial around 10% lower, HDFC Life and ICICI Prudential Life down several percentage points, and SBI Life down comparatively less in the cited market snapshot. Intraday prices naturally change throughout the session. (NDTV Profit)
Insurance Stocks in Focus
| Company | Business Type | Potential Regulatory Sensitivity |
|---|---|---|
| PB Fintech | Digital insurance distribution | Distribution commissions |
| HDFC Life | Life insurer | EoM + distribution mix |
| SBI Life | Life insurer | EoM + distribution mix |
| ICICI Prudential Life | Life insurer | EoM + distribution economics |
| Max Financial | Life insurance holding company | Distribution + EoM |
| LIC | Life insurer | Distribution structure + EoM |
| ICICI Lombard | General insurer | General-insurance EoM + commissions |
| Star Health | Health insurer | Health distribution economics |
The actual effect will depend on each company’s distribution mix, cost structure, product mix and ability to adapt. Analysts have differed in their assessments of which insurers may be more or less affected. (Moneycontrol)
Why PB Fintech Is Getting Special Attention
PB Fintech is structurally different from a traditional insurer.
Its business is closely connected to insurance distribution, making changes to distributor commissions particularly relevant to its economics.
That explains why the market reaction to PB Fintech has been substantially sharper than for some traditional insurers. (NiftyTrader)
However, investors should distinguish between:
Revenue impact
and
long-term business impact.
Lower commissions don’t automatically mean the same percentage decline in profits.
A distributor could potentially respond by:
- Increasing policy volumes
- Improving technology
- Reducing acquisition costs
- Increasing direct digital sales
- Changing product mix
- Improving cross-selling
- Increasing customer retention
Therefore, the final earnings impact cannot be determined solely from the headline commission caps.
The Counterargument: Lower Costs Could Help the Industry
There is another side to the story.
If distribution costs fall, insurers could potentially:
Lower premiums → Improve affordability → Increase insurance penetration → Increase volumes
For example:
Imagine an insurer currently spends ₹20,000 to acquire and distribute policies for every ₹1 lakh of premium.
If technology and regulatory changes eventually bring that cost down to ₹15,000:
Cost saving = ₹5,000
The insurer could theoretically use that benefit through some combination of:
- Better margins
- Lower pricing
- Higher agent productivity
- More competitive products
- Higher customer value
This is one reason why the long-term impact may be different from the immediate stock-market reaction.
Bima Sugam Could Change Insurance Distribution
IRDAI is also pushing digital infrastructure.
The consultation paper discusses Bima Sugam, a digital insurance marketplace, alongside a Public Insurance Registry (PIR).
The broader objective is to move toward a more transparent, technology-enabled and “pull-based” insurance environment, where customers can compare and purchase insurance rather than relying exclusively on traditional sales channels. (Moneycontrol)
This could eventually increase the importance of:
Technology + comparison + customer experience + servicing
rather than simply the size of the sales commission.
Dark Patterns: Another Major Proposed Change
IRDAI has also proposed restrictions on dark patterns in insurance websites and digital platforms.
For example, websites may be restricted from requiring personal information simply to access basic:
- Product information
- Pricing
- Features
- Comparisons
The regulator is seeking greater transparency so consumers can understand products before handing over personal information. (The Economic Times)
What Happens Next?
This is extremely important for investors.
The current document is a:
CONSULTATION PAPER
It is not yet the final regulation.
IRDAI has invited comments and suggestions until:
October 25, 2026
Following consultation, the regulator can modify the proposals before finalising the framework. (The Economic Times)
Therefore, today’s stock-market reaction should not automatically be interpreted as the final economic impact on every insurer.
What Investors Should Monitor
Over the coming weeks, investors can track five major variables:
1. Final commission caps
Will the proposed numbers remain unchanged?
2. Implementation timeline
How quickly will the new EoM limits be introduced?
3. Distributor economics
How will brokers and digital platforms adapt?
4. Bancassurance impact
How much fee income could banks and insurers lose or restructure?
5. Volume versus margin
Will lower distribution costs eventually translate into higher insurance volumes?
IRDAI Insurance Reform 2026: Simple Summary
| Issue | Proposed Change | Possible Industry Effect |
|---|---|---|
| Life EoM | 15% → 12.5% over glide path | Lower operating/distribution costs |
| General EoM | 30% → 20% | Lower cost structure |
| Health first-year commission | Around 15% for distribution entities | Lower distributor payout |
| Health renewal | Around 5% | Lower recurring payout |
| Motor TP distributor commission | 0% | Significant channel impact |
| Long-term life first-year | 20% for distribution entities | Lower acquisition economics |
| Loan-linked insurance | Lower limits | Banks/NBFC fee-income pressure |
| Forced bundling | Proposed restrictions | Greater customer choice |
| Dark patterns | Proposed restrictions | More transparent digital sales |
| Bima Sugam | Digital marketplace | Potentially greater digital distribution |
| Consultation deadline | 25 Oct 2026 | Final rules still pending |
Final Takeaway
The September 24, 2026 insurance-stock sell-off is fundamentally a reaction to a proposed reset of insurance-distribution economics, rather than simply a change in insurance demand.
The proposed framework could reduce commissions and operating expenses, particularly affecting businesses whose economics are heavily dependent on distribution income. At the same time, lower distribution costs could potentially improve affordability, margins or insurance penetration over the longer term.
For investors, the critical distinction is:
Today’s stock-price reaction reflects expectations. The final economic impact will depend on the regulations that IRDAI ultimately implements.
The consultation process, final commission ceilings, implementation schedule and individual companies’ distribution mix will therefore be important factors to monitor.
This article is for educational purposes only and is not investment advice. The IRDAI measures discussed above are proposals as of September 24, 2026 and may change before final implementation.